How Does Contract For Deed Work
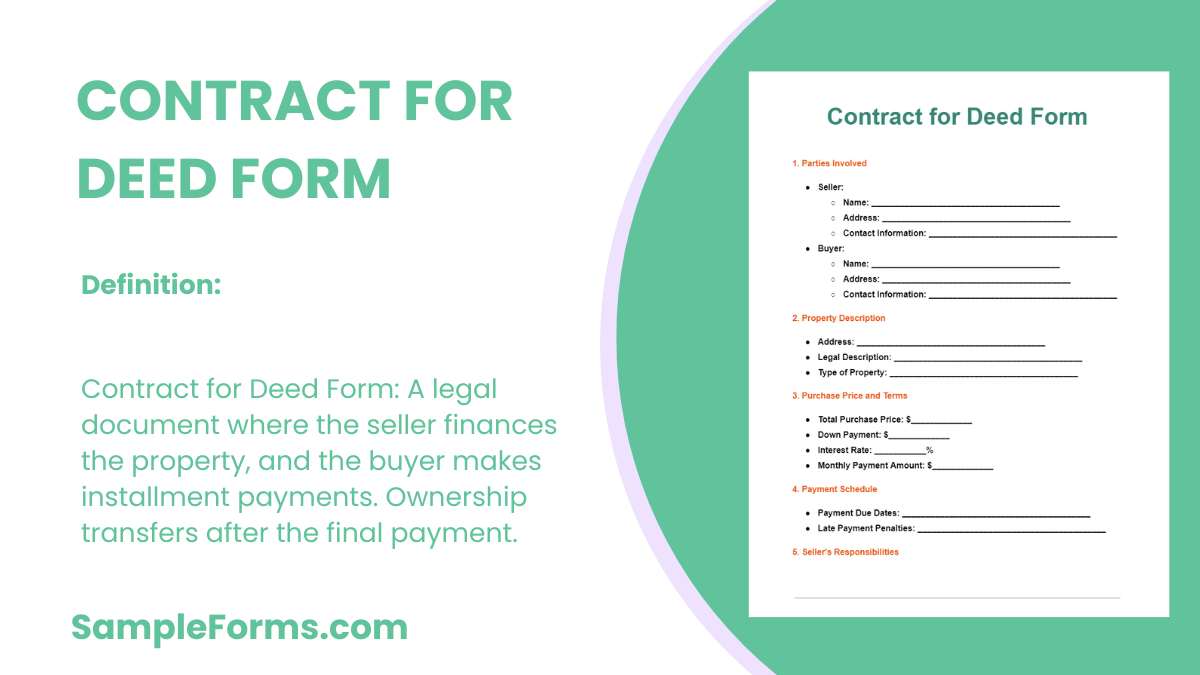
So, you've been hearing about this Contract For Deed thing, huh? Let's grab a coffee and chat about it. You know, like we're sitting at our favorite café, no big words, just friends talking.
What's the Deal with Contract For Deed?
Alright, imagine you're eyeing this super cool house. But, you're like, "Nah, I don't wanna deal with banks right now." Enter Contract For Deed, your new best friend in real estate.
It's like a handshake deal, you and the seller agree on a price, and boom, you've got a contract. No banks, no loans, just you, the seller, and a piece of paper.
Must Read
How Does It Work, You Ask?
Great question! Here's the skinny:
1. The Contract: You and the seller write up a contract. It's like a promise, you agree to pay a certain amount over time, and the seller agrees to sell you the house once you've paid it all off.
2. The Payments: You make regular payments, just like you would with a mortgage. But here's the kicker, these payments aren't going to a bank, they're going straight to the seller.
3. The Title: Now, this is where it gets a tad complicated. The title, that's the legal ownership of the house, stays with the seller until you've made your final payment. It's like you're renting the title, if you will.
But Wait, There's More!
You might be thinking, "This sounds too good to be true." Well, my friend, it's not all sunshine and rainbows. Let's dive into the nitty-gritty.
Pros: The Good Stuff
1. No Bank Involvement: That's right, no credit checks, no loan applications, no waiting for approval. It's just you and the seller.
2. Flexibility: Contract For Deed can be super flexible. The terms can be tailored to what works best for you and the seller.
3. No Down Payment: Yep, you heard it right. No big chunk of cash upfront. You can start making payments right away.
Cons: The Not-So-Good Stuff
1. Risk, Risk, Risk: Here's the thing, you don't own the house until you've paid it off. That means if something goes wrong, you could lose everything you've paid.
2. No Protection: Unlike a mortgage, there's no protection for you if the seller decides to back out. It's a handshake deal, after all.
3. Interest: While there's no bank involved, the seller will usually charge interest. And it can be higher than a traditional mortgage.
So, Should You Do It?
Well, that's the million-dollar question, isn't it? Truth is, it depends. If you're in a hurry to buy a house and don't want to deal with banks, it could be your golden ticket. But if you're not ready to take on that kind of risk, maybe it's not for you.
Here's my advice, grab another coffee, do your research, talk to a real estate lawyer, and really think about it. After all, we're talking about a house here, not a new pair of shoes.
And remember, I'm just a friend giving you some info over coffee. I'm not a real estate expert, so don't make any big decisions based on our little chat. Capisce?