Tax Implications Of Selling Inherited Farmland
Alright, picture this: You've just inherited a sprawling farmland from your great-aunt Edna, complete with a red barn, a windmill that's seen better days, and more cows than you knew what to do with. You're suddenly feeling like a modern-day Green Acres, but hold your overalls, because before you can say "moo," you've got to understand the tax implications of selling that land.
First Things First: What's Your Base?
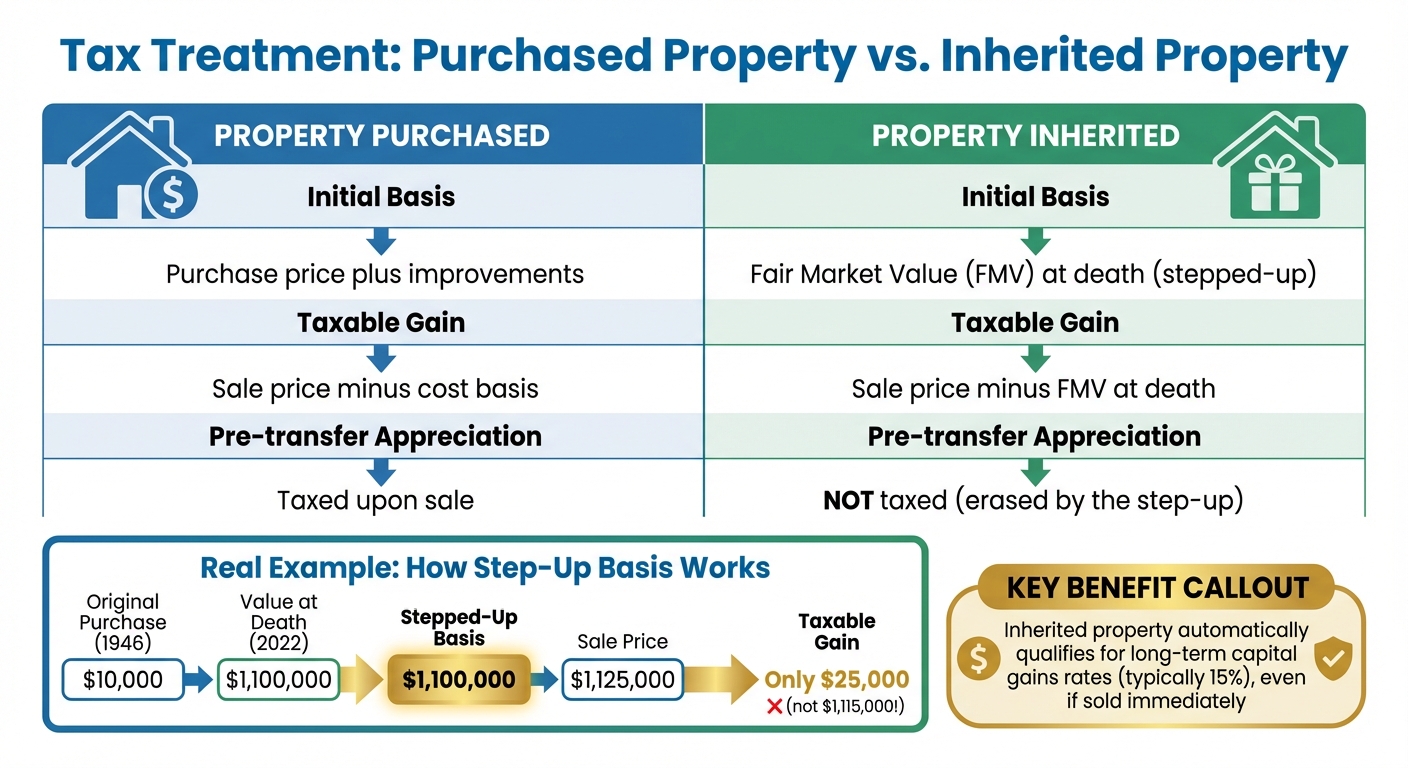
Before we dive into the nitty-gritty, let's talk about your basis. No, not the dance move, the tax term. Your basis is the value of the property when you inherited it. If you're thinking, "But I didn't inherit any money, just a bunch of hay and a tractor," well, that's because the IRS loves to complicate things. They've got a special term for this, too: "stepped-up basis." It means your basis is the fair market value of the property on the date of your great-aunt Edna's passing.
Now, if you're thinking, "Great, so I get to sell it for a profit without paying taxes," hold your horses, because the IRS isn't done with you yet.
Must Read
Capital Gains: The Tax That Keeps on Taking
When you sell that farmland, any profit you make is considered a capital gain. And guess who loves capital gains? The IRS, that's who. They've got a special tax just for them, called the capital gains tax. The rate varies depending on your income, but it can go up to 20% for single folks making over $40,000 a year. Ouch, right?
But wait, there's more! If you sell the land within a year of inheriting it, you'll be taxed at your regular income tax rate. And if you thought the capital gains tax was high, well, buckle up, buttercup.
Death and Taxes: The Only Two Certainties in Life
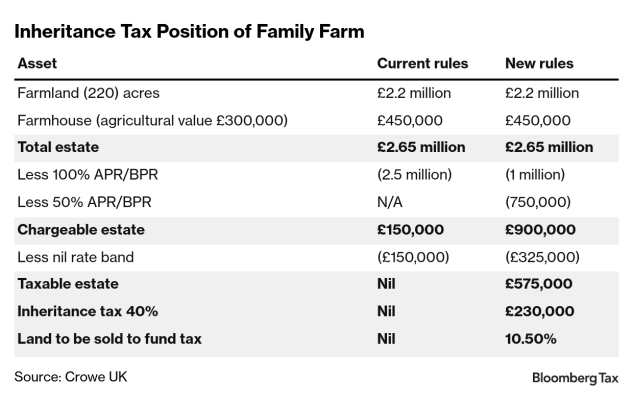
Now, let's talk about estate tax. You might be thinking, "But I didn't die, my great-aunt did. Why do I have to pay her taxes?" Well, the IRS doesn't care about your logic. If the value of your great-aunt's estate exceeds the exemption amount (which was $11.7 million in 2021, but who's counting?), then you might have to pay estate tax. And the cherry on top? The estate tax rate is a whopping 40%.
But don't worry, most people don't have to pay estate tax. In fact, only about 0.2% of estates are affected by it. So, unless your great-aunt was secretly a billionaire farmer, you're probably in the clear.
Section 1031: The Farmland's Best Friend
Now, before you start planning your escape to a tax-free island, let me tell you about Section 1031. It's a tax law that lets you defer paying capital gains tax if you exchange one investment property for another. So, if you sell your great-aunt's farmland and buy another piece of farmland (or any other investment property) within a certain time frame, you can delay paying those capital gains taxes. It's like the IRS giving you a timeout, but with strings attached.
But here's the catch: You've got to use the property for business or investment purposes, and you've got to follow a bunch of rules. And if you sell the new property before you die, you'll owe capital gains tax on the deferred gain, plus any new gain. Fun, right?
When in Doubt, Ask a Pro
Alright, I know what you're thinking: "This is all way too complicated for me. I just want to sell my farmland and buy a fancy city apartment." I get it, taxes are no joke. That's why it's always a good idea to consult with a tax professional or an estate planning attorney. They can help you navigate the complex world of tax laws and make sure you're not leaving any money on the table (or giving too much to the IRS).
So, there you have it. The tax implications of selling inherited farmland, served with a side of humor and a dash of exaggeration. Now go forth, sell that land, and remember: the IRS might take a bite out of your profits, but at least they won't eat your hay.