What Age To Sign Up For Social Security
Alright, gather 'round, folks. We're about to dive into the fascinating world of Social Security, and I promise, it's not as dry as a week-old cracker. We're gonna chat about that all-important question: when's the best age to sign up?
First Things First: What's Social Security?
Imagine Social Security as your friendly neighborhood superhero, always there to lend a helping hand when you need it most. It's a government program that provides financial assistance to retirees, survivors, and the disabled. It's like your very own financial safety net, ready to catch you when you decide to hang up your work boots.
So, When's the Magic Number?
Now, you might be thinking, "When should I sign up for this superhero service?" Well, my friend, it's not as simple as choosing your favorite flavor of ice cream. The age you sign up can make a big difference in how much you'll receive each month.
Must Read
Full Retirement Age: The Goldilocks Zone
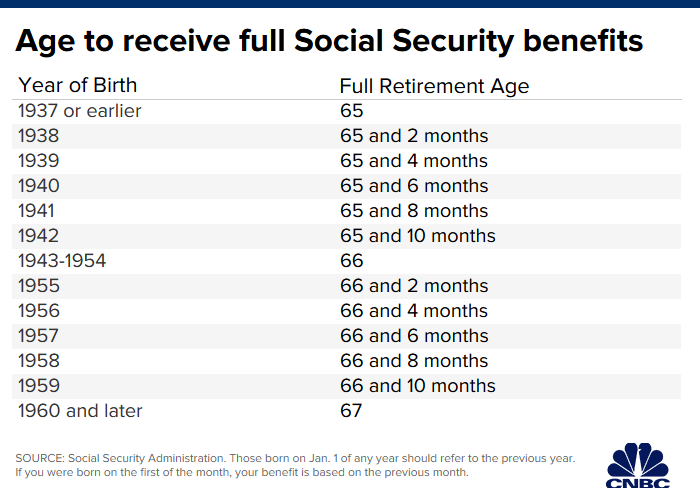
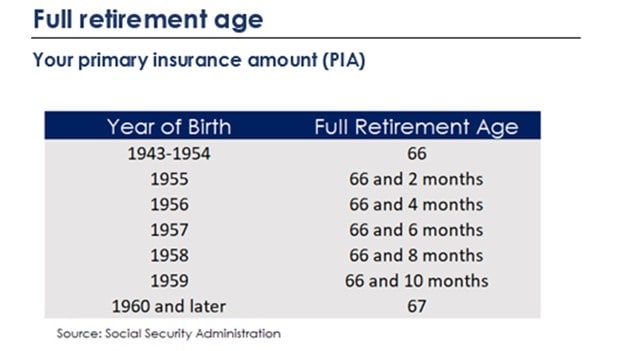
Let's start with the full retirement age, or what I like to call the "Goldilocks Zone." This is the age when you can start receiving your full Social Security benefit. For folks born between 1943 and 1954, that's 66. It's like that perfect bowl of porridge - not too hot, not too cold, just right.
But here's the thing, you can start receiving benefits as early as age 62, or as late as 70. It's like choosing when to have your birthday party - the earlier you start, the more guests you'll have (in this case, more months of payments), but the less cake you'll get per guest (smaller monthly benefit).
Early Bird Gets the Worm... But Not the Whole Cake
Signing up early might seem like a great idea, but remember, you're getting a smaller slice of the cake. If you start at 62, your monthly benefit could be as much as 30% less than if you'd waited until your full retirement age. It's like ordering a kid's meal when you're really hungry - sure, you get something to eat, but you're still left wanting more.
But hey, if you need the money and you're healthy, why not take it? It's like finding a $20 bill on the street - you didn't plan on it, but you'll sure take it if it's there!
The Late Bloomer's Advantage
On the other hand, if you wait until after your full retirement age, your benefit will increase. It's like waiting for your cake to cool before you have a slice - it's worth the wait, and you get a bigger piece. For every year you delay past your full retirement age, your benefit increases by about 8%. So, if you wait until you're 70, your benefit could be as much as 76% more than if you'd started at 62.
But remember, you're not getting any younger, and life's full of surprises. You might need that money sooner rather than later, so it's a balancing act.
When to Sign Up: A Tale of Two Friends
Let me tell you about my two friends, Jim and Pam. Jim's always been a planner, the kind of guy who saves his lunch money for a rainy day. He waited until he was 67 to sign up for Social Security. Pam, on the other hand, lives for the moment. She started receiving benefits at 62. Guess who's getting a bigger check each month?
But here's the kicker - Jim's still working, so he's not relying on Social Security yet. And Pam? Well, she's enjoying her retirement, traveling the world, and living her best life. So, who's really winning here?
To Each Their Own
There's no one-size-fits-all answer to when you should sign up for Social Security. It depends on your health, your financial situation, and your plans for retirement. It's like choosing a flavor of ice cream - some people love chocolate, others prefer vanilla. The important thing is to make an informed decision.
So, when's the best age to sign up for Social Security? It's like asking, "When's the best time to have a baby?" or "When's the best time to buy a house?" It's a personal decision, and it's all about what works best for you.
But remember, folks, knowledge is power. The more you know about Social Security, the better equipped you'll be to make the right decision for you. So, do your research, talk to a financial advisor, and most importantly, have fun with it. After all, it's your money, your future, and your retirement. You deserve to enjoy every minute of it.